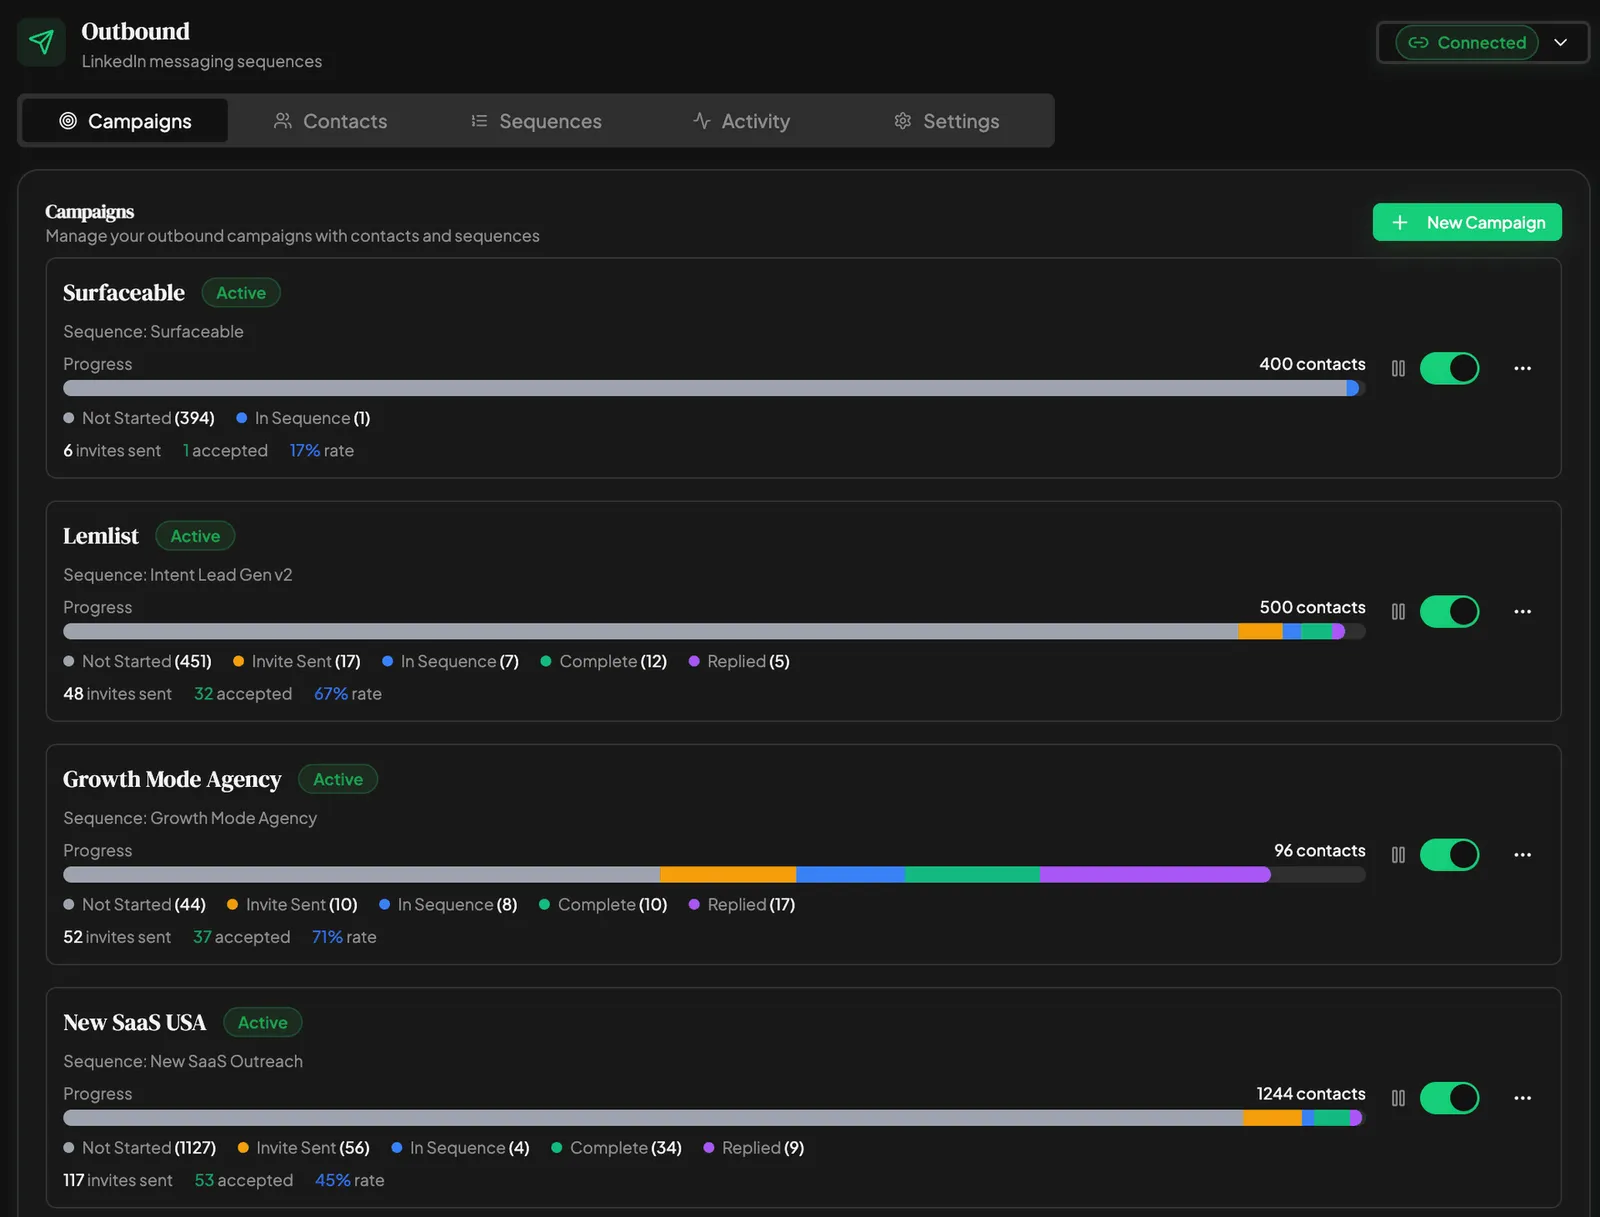
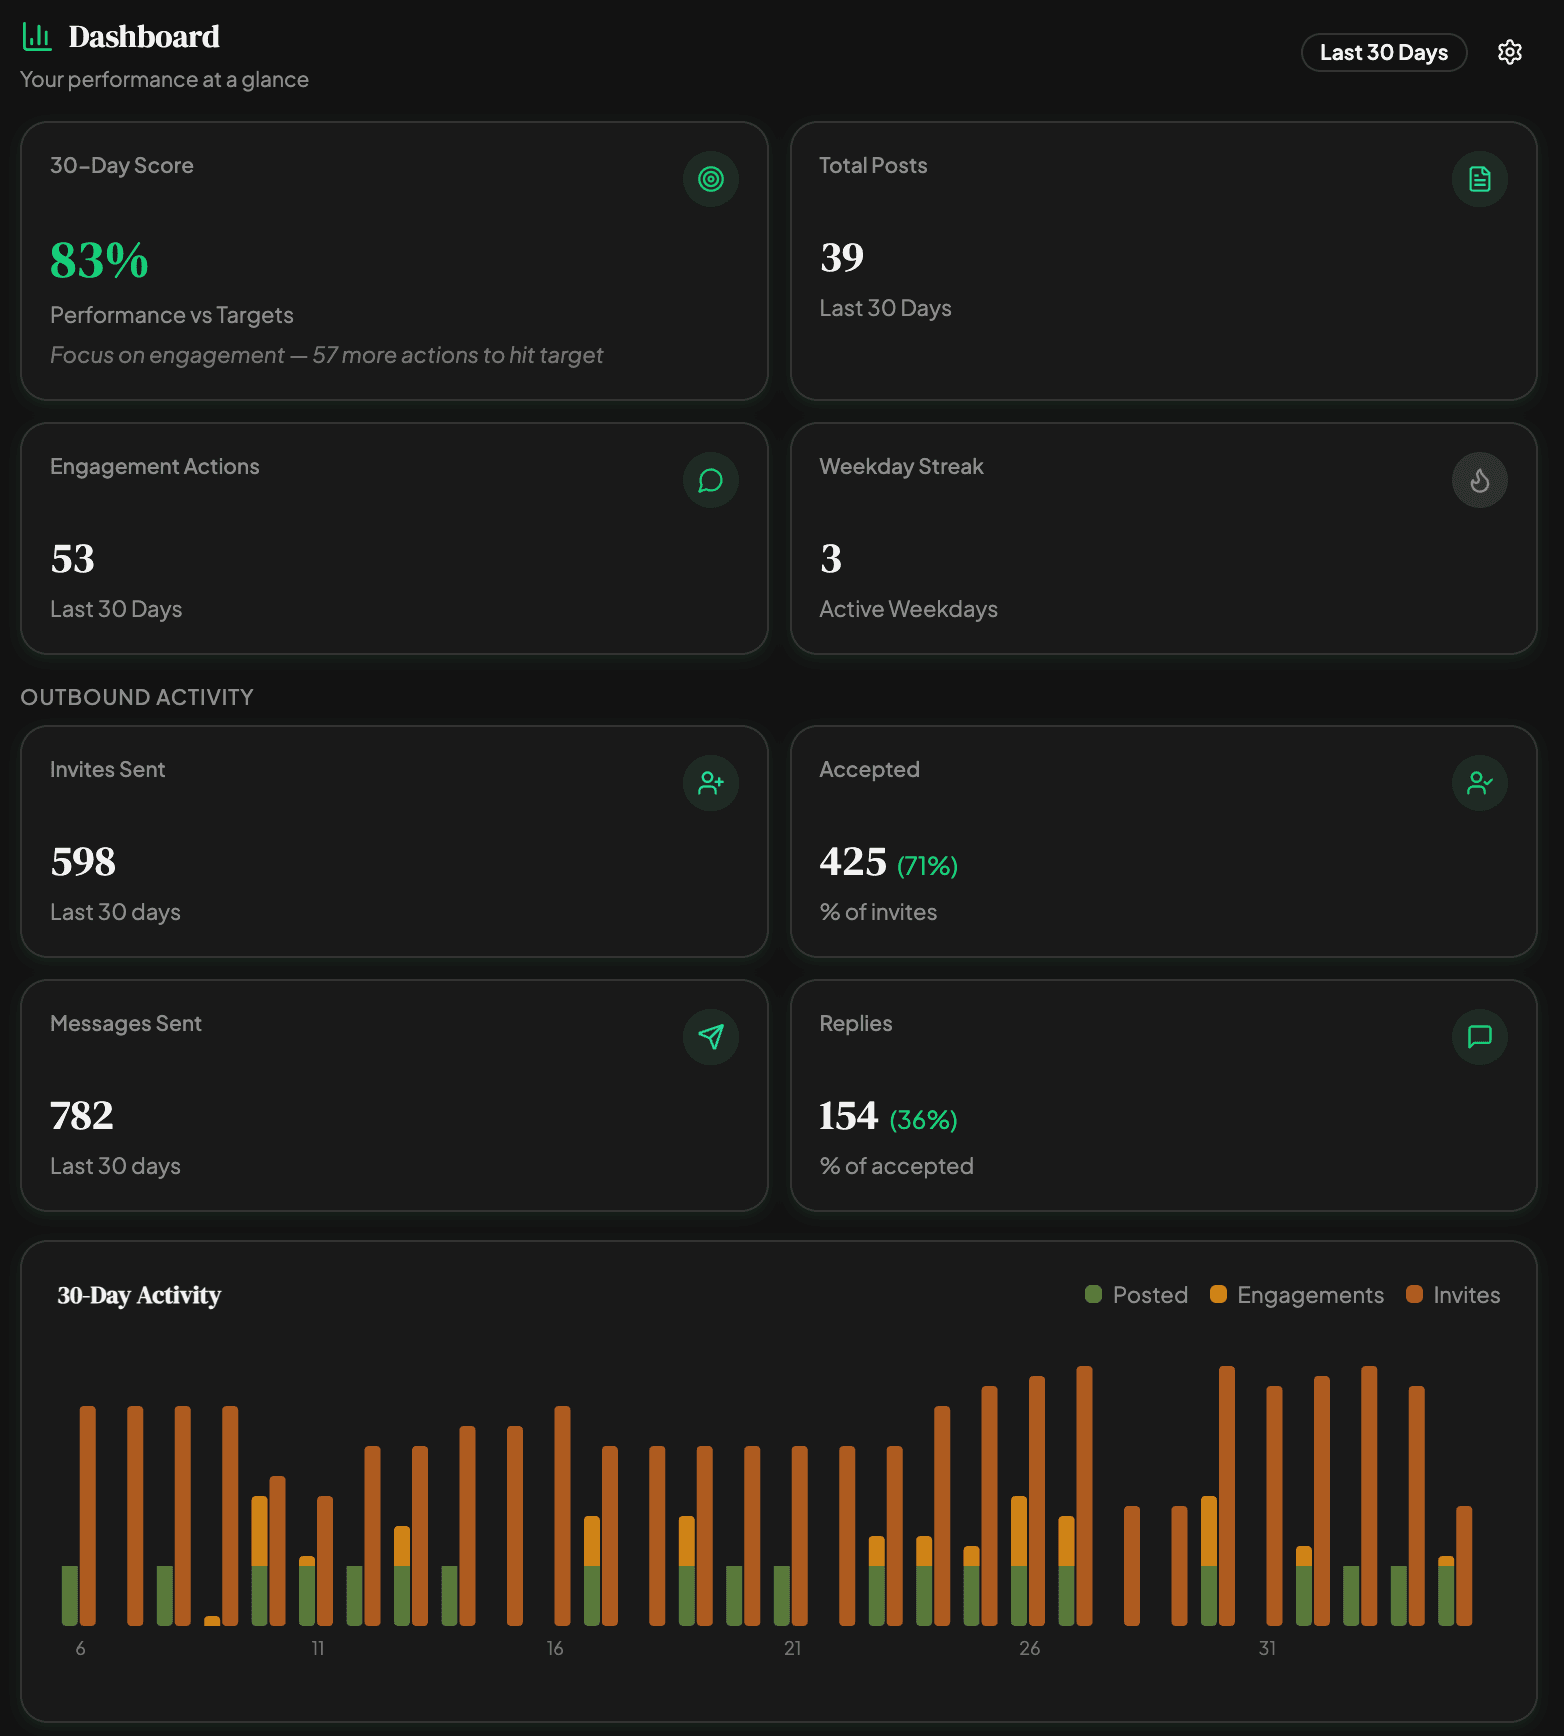
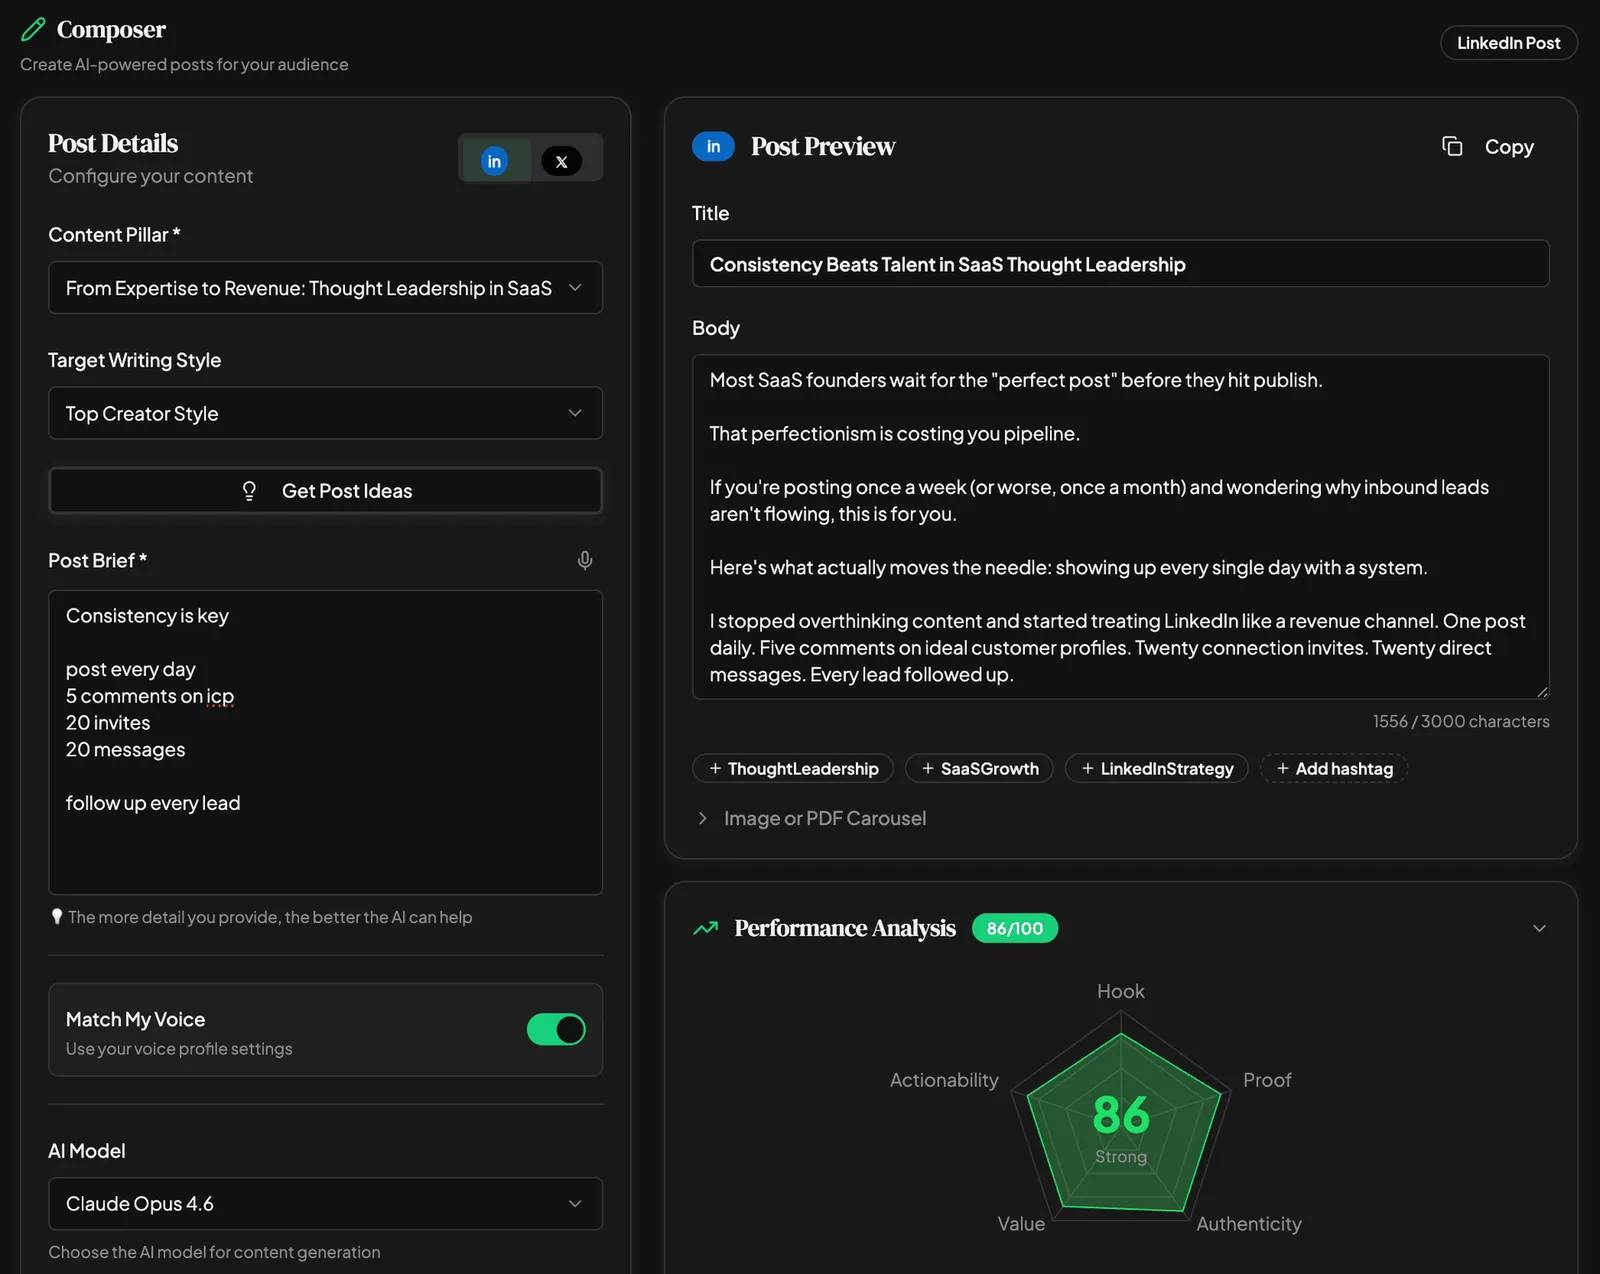
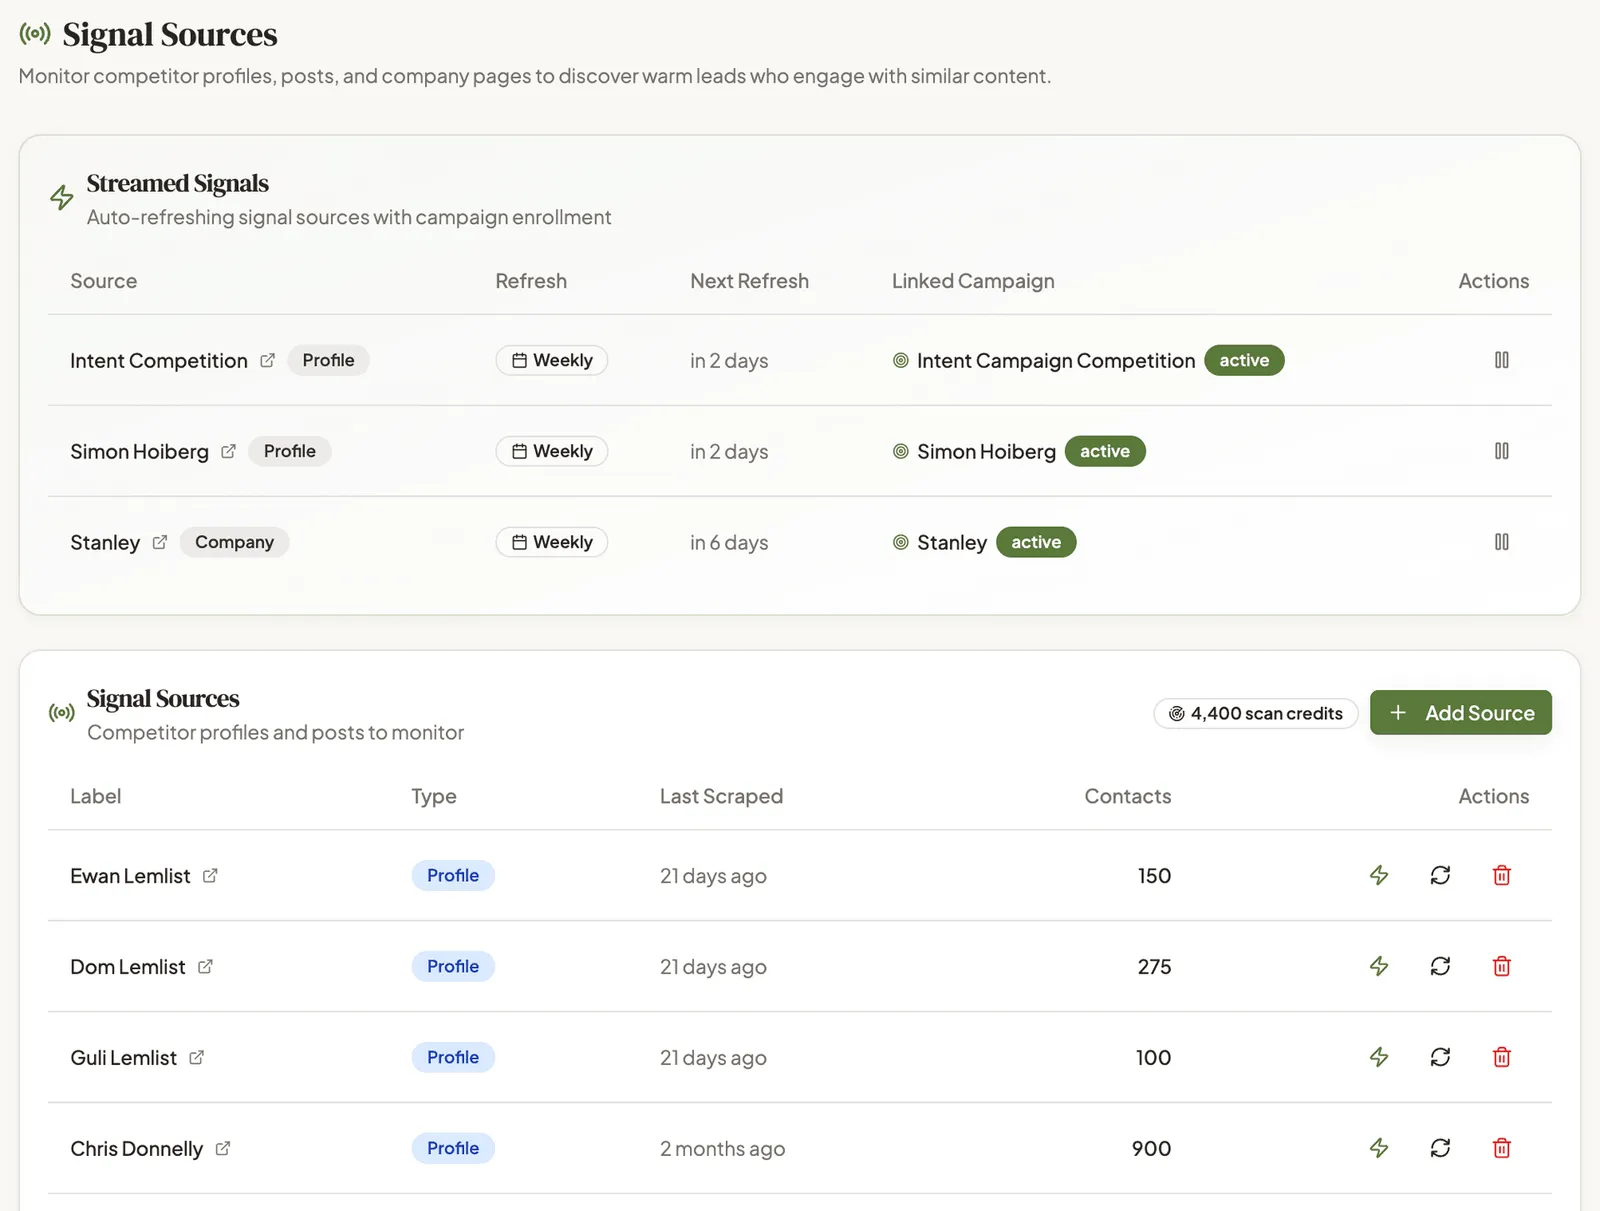
Ghost is the all-in-one GTM platform for B2B founders and small revenue teams: an AI SDR, a 600M-contact database, LinkedIn + email outreach, intent signals and a built-in CRM, on one plan. Raising £250k SEIS to prove a repeatable acquisition engine.
A founder doing their own GTM pays for a lead database, a sequencer, LinkedIn automation, a content scheduler and a CRM. None of them talk to each other, and the gaps between them are where most pipeline dies.
Apollo for leads. Lemlist for email. Expandi for LinkedIn. Taplio for content. HubSpot for deals. None of them talk to each other, and each one is another bill.
Cold DMs and emails go to lists that have never heard of you. Reply rates are 2–4%. The prospect has no reason to respond, and the sender has no signal to reference.
Replies sit across LinkedIn, Gmail and a CRM nobody updates. Warm signals go unnoticed and deals go quiet, because no single system sees the whole picture.
The fix isn't another point tool. It's one platform that runs the whole motion — find, warm, reach, close — with intent signals connecting every step.
All-in-one GTM for founders and small revenue teams. Point tools each own one step; Ghost owns the whole motion, with intent signals as the connective tissue no point tool has.
Every VC is funding “AI SDR” startups that promise to replace your sales team. Most are gimmicky. Ghost takes a different position: the AI does the work. You stay in control.
Ghost doesn't replace judgment — it removes grunt work. You set the ICP once. The AI finds the leads, writes the sequences, tracks the signals, and enrols the contacts. You review. You approve. You close.

Find buyers → warm them up → reach them with context → close in the built-in CRM. Each step feeds the next, and every signal stays in one place.
Fully bootstrapped — zero marketing spend. Every pound of ARR came from founder-led outreach. The raise systematises what's already working so growth doesn't depend on one person.
Received and rejected a buy-out while at early ARR. The view: this is worth materially more than the offer on the table. That's not bravado — it's the reason for this raise.
The product is built. The category is proven. The only missing piece: a repeatable, non-founder-dependent acquisition engine. That's what this £250k buys — 18 months of paid experiments, two GTM hires, and the proof needed to raise Seed at 3× the valuation.
The right founder profile to build, sell, and scale a B2B SaaS — and personally architect the AI behind it.
LinkedIn is the largest B2B audience on the planet. The tools market around it is growing fast — data tools, outbound tools, content tools, intent data, CRMs. Founders end up buying four or five of them, and none connect.
As Ghost accumulates more intent signal data, brand voices and pipeline outcomes, the platform becomes harder to replicate. And because a customer's data, sequences and deals all live in Ghost, the longer they stay, the more of their GTM runs on it.
First 3–4 months: ~£20–25k as pure channel experimentation while the growth hire fixes website conversion. Remaining ~£70k scales only into channels proving sub-12-month payback. Protects against burning the largest budget line before the funnel converts.
A Seed round of £1–2m at £4–6m pre-money — a 3× step up on the current valuation. SEIS investors benefit from the full valuation uplift at Seed, with no dilution until that next round.
| Instrument | SEIS UK tax-advantaged seed scheme |
| Raise amount | £250,000 (full SEIS lifetime ceiling) |
| Pre-money | £2m |
| Dilution | ~11% |
| All-in dilution (inc. 10% option pool) | ~19–22% |
| Runway | 18 months |
| Advance Assurance | In progress — filing via new clean entity |
| Round | Raise | Pre-money | Founder stake |
|---|---|---|---|
| Start | — | — | 100% |
| SEIS This round | £250k | £2m | ~80% |
| EIS / Seed | £750k | £4m | ~64% |
| Series A | £3m | £12m | ~51% |
Raise the right amount to hit each inflection, then raise again at a materially higher valuation. Staged dilution at rising valuations keeps meaningful founder ownership — and SEIS investors enter at the lowest valuation in Ghost's history.
Ghost has the product, the positioning, and early traction. This raise proves one thing: that we can acquire customers at scale through repeatable channels — not just founder hustle. Hit that, and the Seed round follows at 3× the valuation.
Working document. Valuation, dilution and structure are estimates. Confirm SEIS structure and Advance Assurance with a specialist accountant (SeedLegals, Harper James) before committing capital.